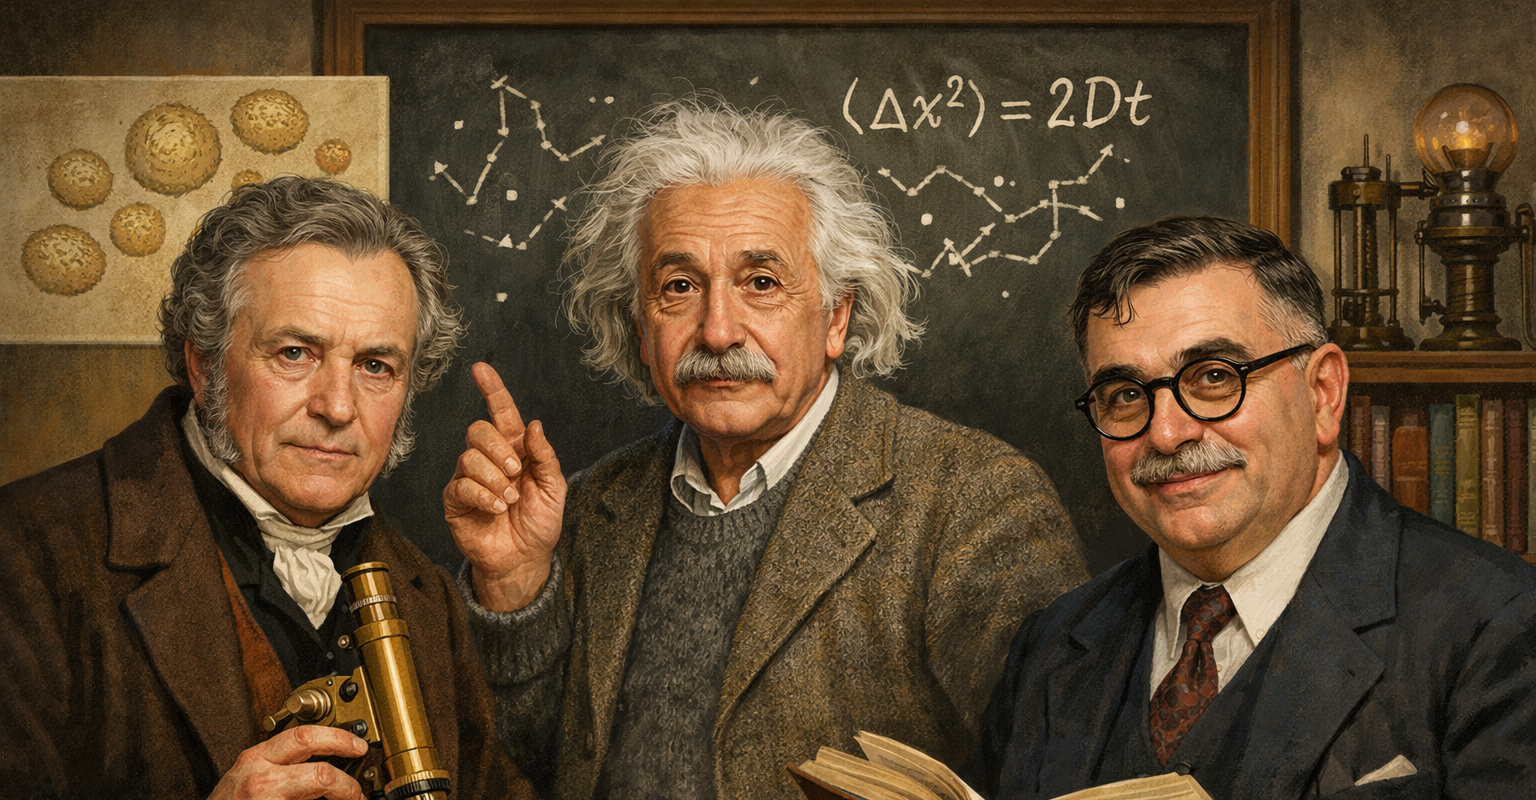
,

Chapter 1: The Mysterious Movement of Mr. Brown

Chapter 1: The Mysterious Movement of Mr. Brown

Of how a botanist and two geniuses unknowingly laid the foundations of Mathematical Finance

In this episode, we trace the emergence of Brownian motion from its historical origins to its mathematical structure.

We begin with a brief historical account, examining Robert Brown’s botanical observations and Einstein’s theoretical explanation of molecular motion. We then introduce the concept of stochastic processes and develop the definition and fundamental properties of Brownian motion as the cornerstone of modern continuous-time stochastic modelling.

What began as a scientific curiosity would eventually become one of the central mathematical instruments of Quantitative Finance.

This episode is currently in preparation and will be released shortly.
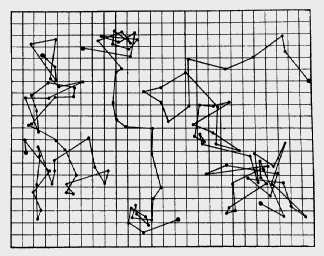
Figure 1.1: Brownian motion of particles in a suspension
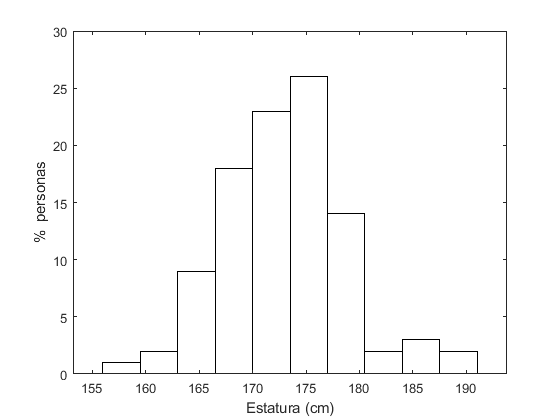
Figure 1.2: Histogram
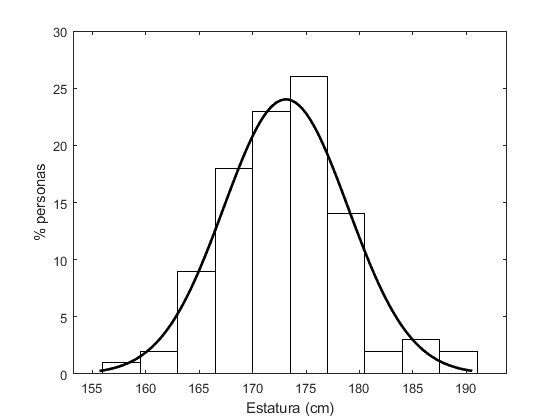
Figure 1.3: Fit to Gaussian density
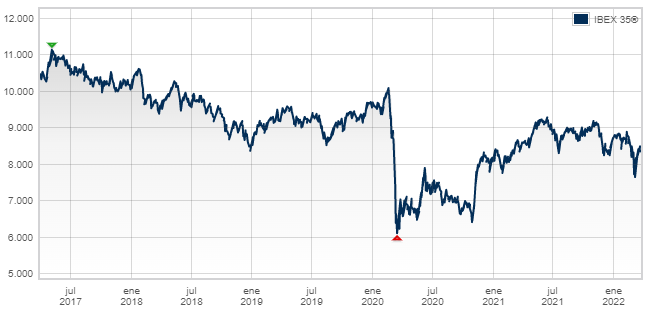
Figure 1.4: IBEX 35 historical data
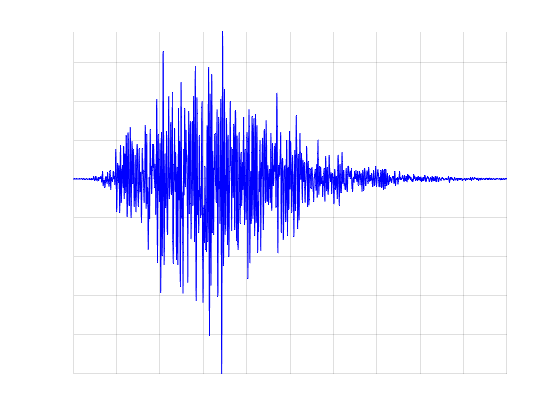
Figure 1.5: Seismogram
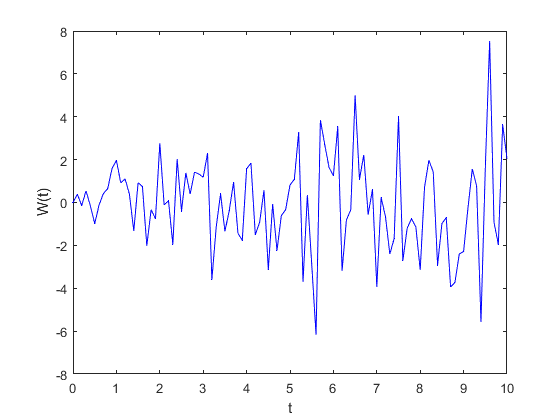
Figure 1.6: Brownian motion trajectory
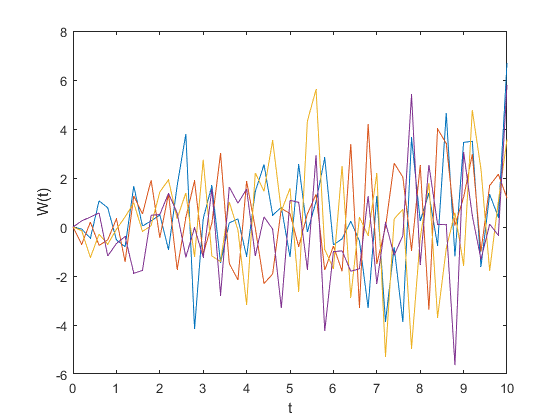
Figure 1.7: Different trajectories of a Brownian motion
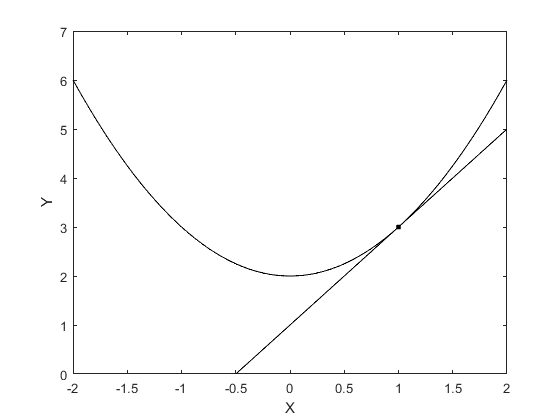
Figure 1.8: Tangent to a curve
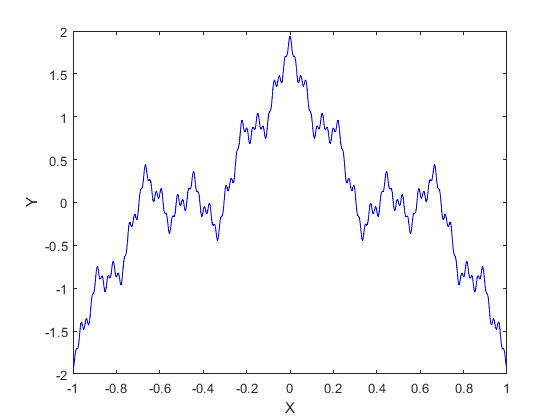
Figure 1.9: Weierstrass function
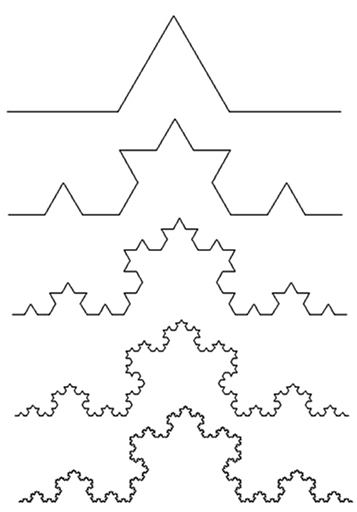
Figure 1.10: Koch curve
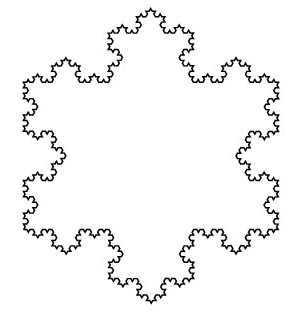
Figure 1.11: Koch snowflake
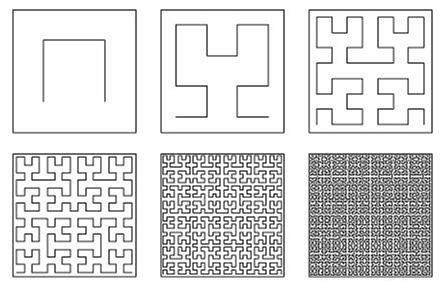
Figure 1.12: Construction of the Hilbert curve
Tags

0 responses to “Chapter 1: The Mysterious Movement of Mr. Brown”

Leave a Reply

Your email address will not be published. Required fields are marked *

Math notation supported: \( ... \) for inline formulas and $$ ... $$ for display equations

Follow Us On Social Media

Academic Contributors

Alberto Bueno Guerrero

Lead Author

PhD in Banking & Finance

BSc Physics (Theoretical Physics)

BSc Economics (Quantitative Economics)

Independent Researcher in Quantitative Finance

Educational content author