For many students, stochastic calculus is one of the first major mathematical challenges they encounter. Brownian motion, Itô integrals and stochastic differential equations soon become essential tools for studying derivative pricing, risk management and quantitative modelling.
A common question at this stage is: Would it be worth building a solid foundation before the programme begins? At QuantPhi, we believe the answer is yes.
But we also believe that a good textbook should do much more than help you prepare for your first lectures. It should become a trusted reference that you can return to throughout your Master’s degree, and even later in your professional career, whenever you need to revisit a concept, understand a proof, or deepen your understanding of stochastic calculus.
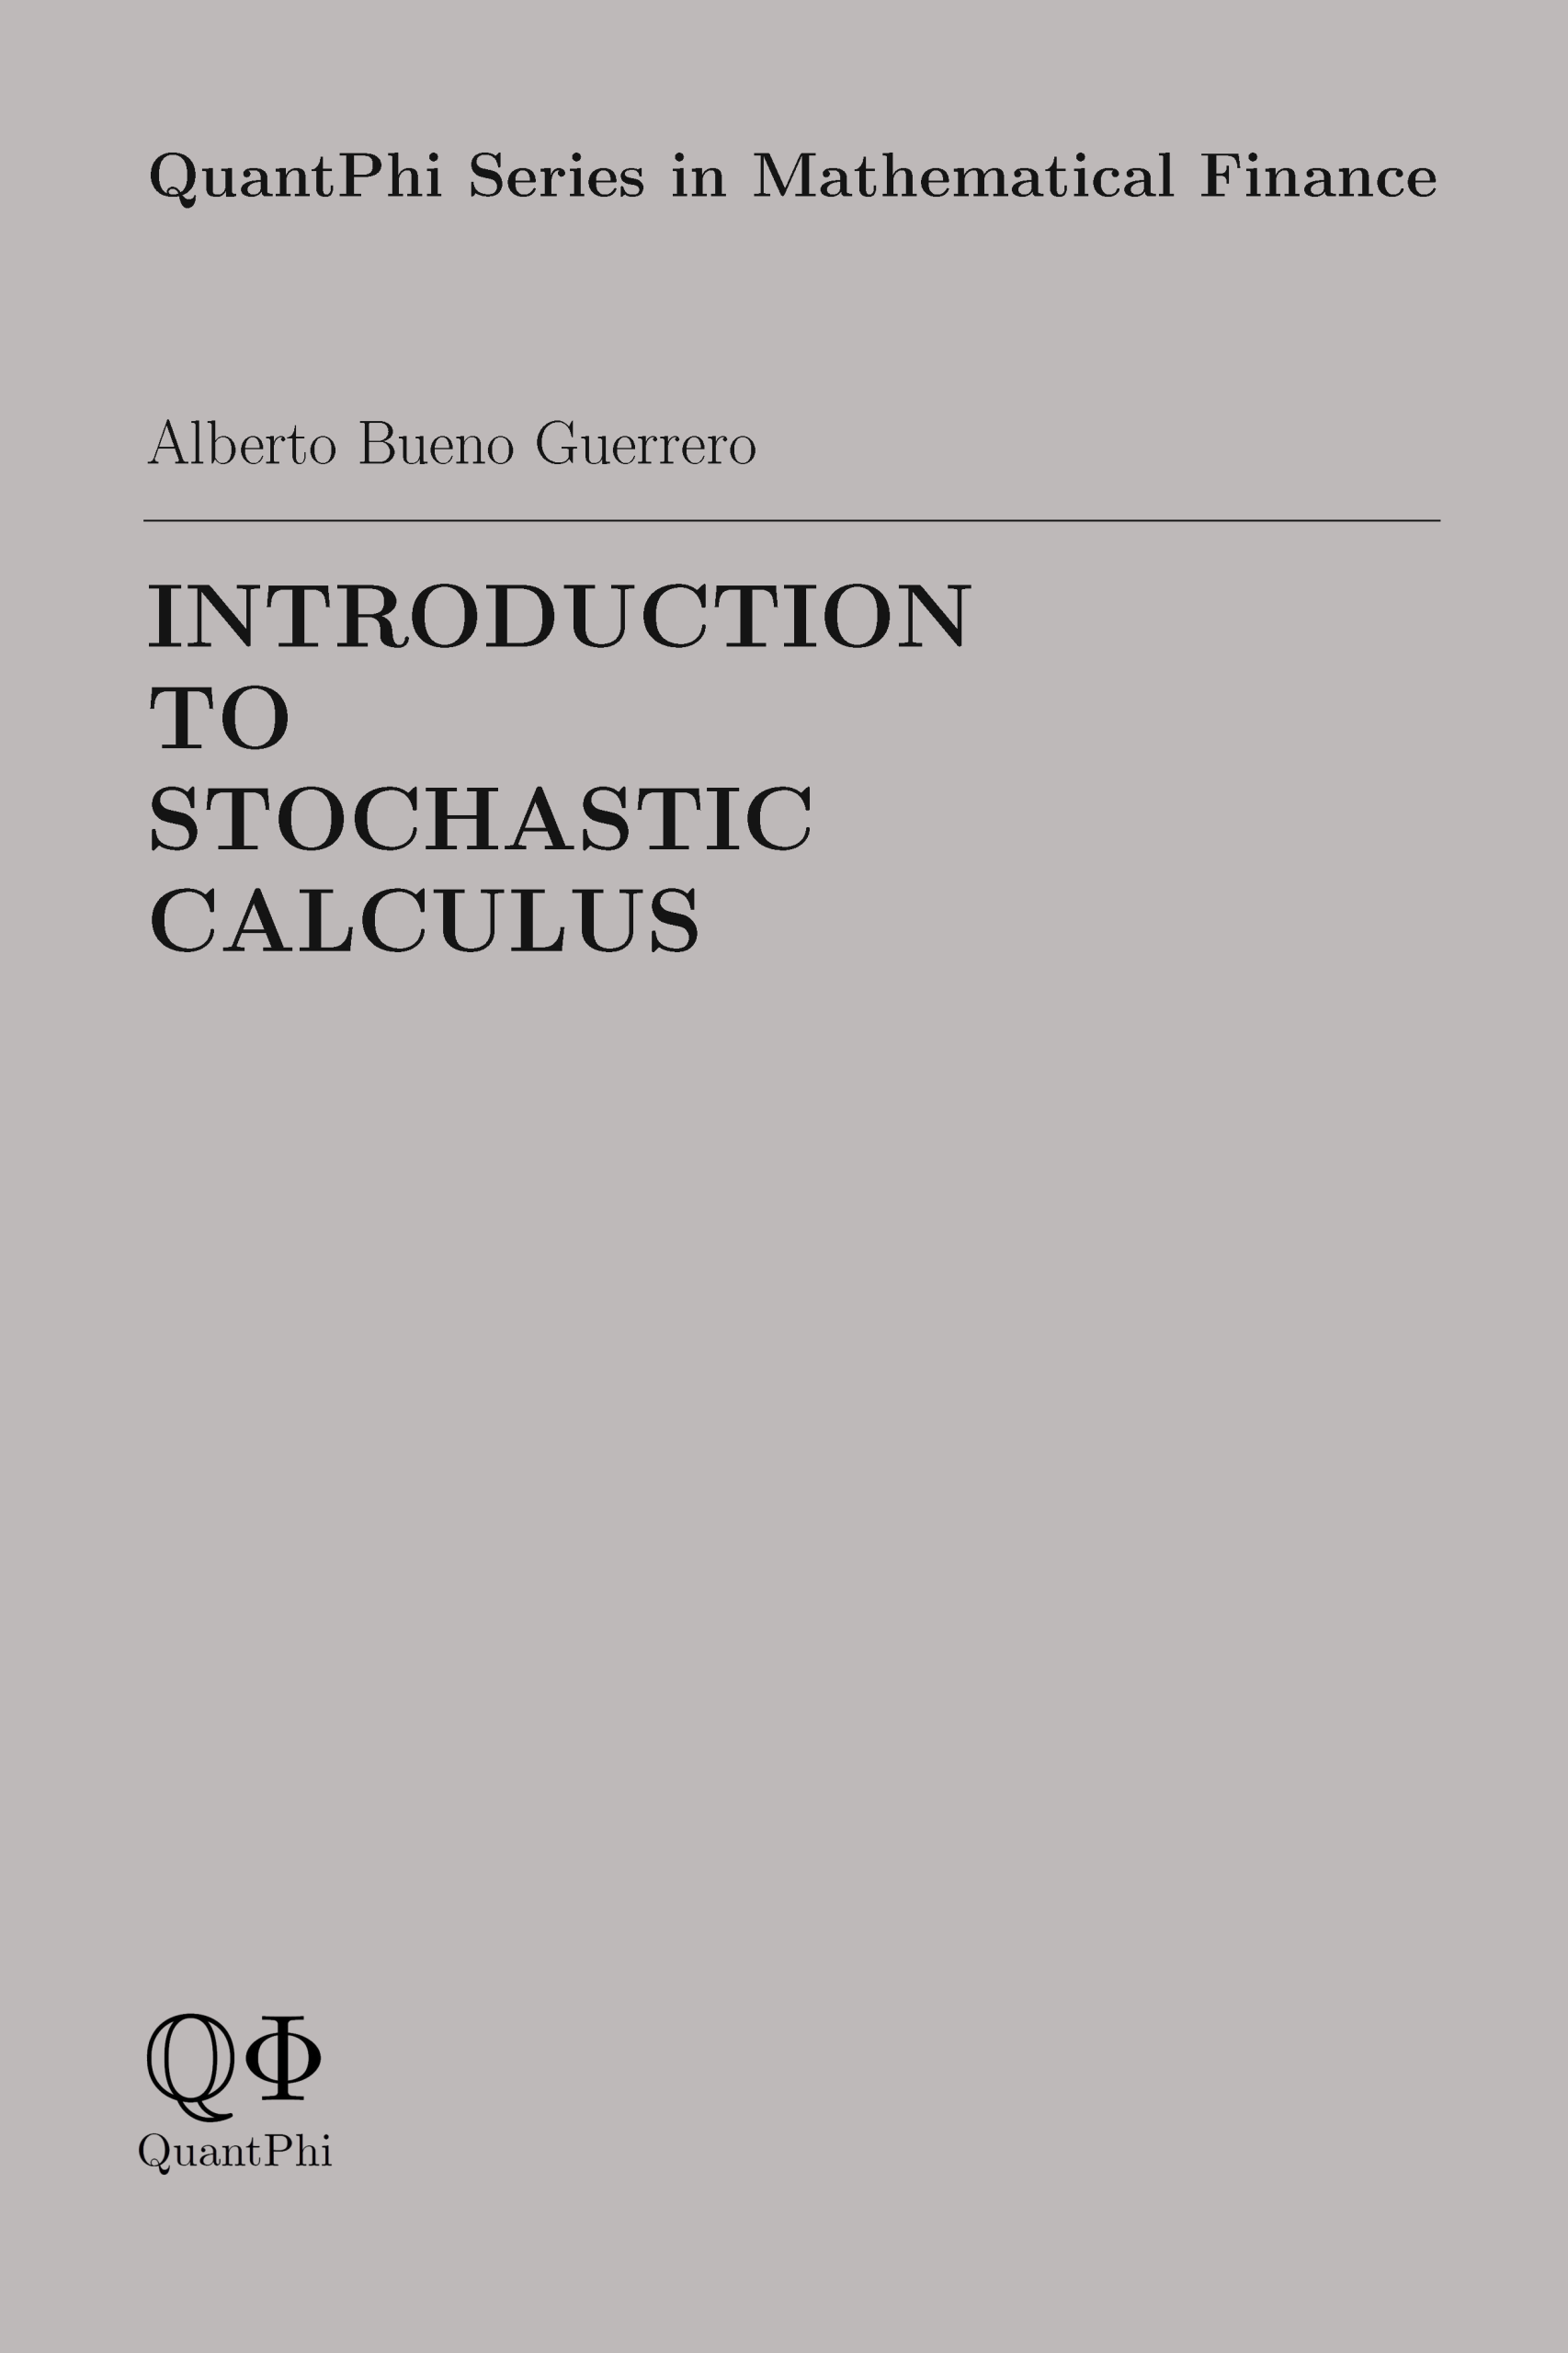
That is precisely the philosophy behind Introduction to Stochastic Calculus, the first volume in the QuantPhi Series in Mathematical Finance. The book has been designed to provide:
📘 A rigorous and mathematically sound introduction to stochastic calculus.
🎓 Clear explanations and detailed proofs to support genuine understanding rather than rote learning.
📚 A long-term reference that remains useful throughout your studies and beyond.
Below you can find the book cover and the table of contents, allowing you to explore its structure and decide whether it matches your learning goals. It is available on Amazon: https://amzn.eu/d/00hdKiza
More information about our books on https://quant-phi.com/our-books/
Leave a Reply