
Trending Tags
-
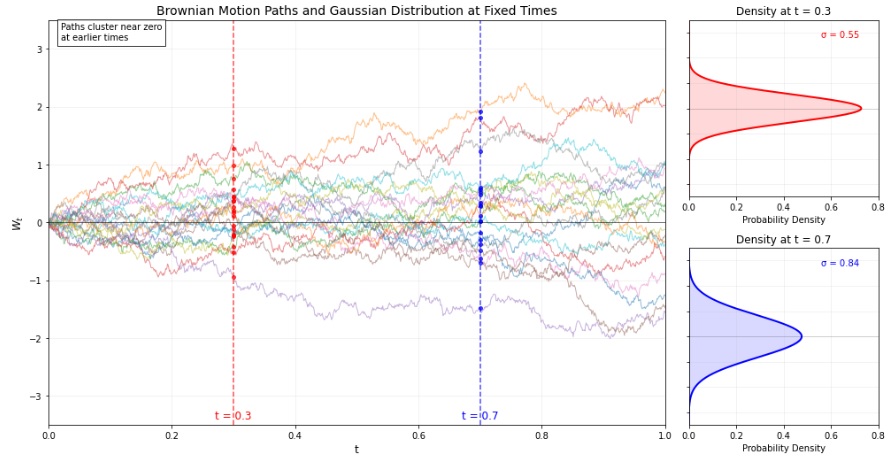
First module of the course Introduction to Stochastic Calculus: Brownian Motion
📚 It’s here! Brownian Motion, the first module of QuantPhi’s Introduction to Stochastic Calculus, is now available. We’re delighted to share…
-
New Book: Introduction to Stochastic Calculus
For many students, stochastic calculus is one of the first major mathematical challenges they encounter. Brownian motion, Itô integrals and stochastic…
Latest Articles
-
First module of the course Introduction to Stochastic Calculus: Brownian Motion
Read More: First module of the course Introduction to Stochastic Calculus: Brownian Motion📚 It’s here! Brownian Motion, the first module of QuantPhi’s Introduction to Stochastic Calculus, is now available. We’re delighted to share the release of this first module in our…
-
New Book: Introduction to Stochastic Calculus
Read More: New Book: Introduction to Stochastic CalculusFor many students, stochastic calculus is one of the first major mathematical challenges they encounter. Brownian motion, Itô integrals and stochastic differential equations soon become essential tools for studying…
-
2026 INFORMS Conference on Financial Engineering and Fintech
Read More: 2026 INFORMS Conference on Financial Engineering and FintechThe INFORMS Conference will feature the latest developments in financial engineering and fintech. The conference aims to enhance worldwide collaboration and provide an ideal platform for local students and…
Follow Us On Social Media
Academic Contributors
Alberto Bueno Guerrero
Lead Author
PhD in Banking & Finance
BSc Physics (Theoretical Physics)
BSc Economics (Quantitative Economics)
Independent Researcher in Quantitative Finance
Educational content author